

Last updated
HDB Upgrader Mortgage Guide: Step-by-step Tips & Tools for Financing Your Condo or EC Move
So you’ve hit your MOP, built up some equity in your HDB flat, and now you’re eyeing that shiny new condo or Executive Condominium. Exciting times ahead! But here’s the thing, financing an upgrade isn’t as straightforward as your first HDB purchase. The numbers are bigger, the rules are different, and one wrong move could cost you tens of thousands of dollars.
Don’t worry though. This guide breaks down everything you need to know about financing your HDB-to-condo or EC move in 2026, step by step, with real numbers and actionable tips you can use today.
Step 1: Check Your Loan Eligibility First
Before you start browsing ShowFlat schedules, you need to know exactly how much you can borrow. Your borrowing power depends on one critical factor: will this condo or EC be your first or second property at the point of purchase?
Here’s where it gets interesting:
| Scenario | Loan-to-Value (LTV) | Down Payment Required |
|---|---|---|
| First property (HDB fully sold/paid) | Up to 75% | Minimum 25% |
| Second property (buying before selling HDB) | Up to 45% | Minimum 55% |
Picture this: you’re eyeing a $1.5 million condo. If you sell your HDB first, you need $375,000 upfront. Buy before selling? That jumps to a whopping $825,000. That’s a $450,000 difference just from timing alone.
Pro tip: Get mortgage pre-approval from at least 2-3 banks before you start viewing properties. This confirms your actual borrowing limit and prevents nasty surprises down the road.
Step 2: Understand the TDSR Cap (This Is Non-Negotiable)
Even if you qualify for a high LTV, your income determines the final loan amount. Singapore’s Total Debt Servicing Ratio (TDSR) caps your total monthly debt obligations at 55% of your gross monthly income.
This includes:
- Your new mortgage payment
- Existing car loans
- Credit card minimum payments
- Any other outstanding loans
Let’s talk numbers. Say your household income is $12,000/month. Your maximum allowable debt servicing is $6,600. If you’re already paying $1,500 for a car loan, only $5,100 remains for your new mortgage, which significantly limits your borrowing power.
Quick affordability reference:
| Monthly Household Income | Estimated Affordable Property Price |
|---|---|
| $6,000 | $450,000–$500,000 |
| $10,000 | $700,000–$800,000 |
| $15,000 | $1,000,000–$1,200,000 |
Golden rule: Keep your mortgage payment under 30% of household income for long-term financial comfort. Just because you can borrow more doesn’t mean you should.
Step 3: Map Out Your Upfront Costs
When it comes to upgrading, the down payment is just the beginning. Here’s the full breakdown of what you’ll need before collecting keys:
At Option-to-Purchase (OTP) Stage:
- Option Fee: 1% of purchase price (cash only)
- Balance Deposit: 4% of purchase price
At Sale & Purchase Agreement:
- Down Payment: 15-20% of purchase price (CPF-eligible for up to 20%)
- Buyer’s Stamp Duty (BSD): Tiered rates, approximately $24,600 for a $1 million property
- Legal Fees: $2,500–$3,500
For Properties Under Construction (BUC/EC):
Progressive payments kick in every 6 months:
- Foundation complete: 10%
- Reinforced concrete: 10%
- Walls complete: 5%
- Ceiling/roofing: 5%
- And so on until TOP…
Real example: For a $1.2 million EC, expect to pay approximately $300,000–$350,000 before you even step foot in your new home (including stamp duties and legal fees).
Step 4: Choose Your Loan Type Wisely
Unlike HDB purchases where you could tap HDB loans, upgrading to a condo or EC means bank loans only. Here’s what you’re working with in 2026:
| Factor | Bank Loan Details |
|---|---|
| Maximum Tenure | Up to 30 years |
| Rate Type | Fixed (2-3 years) then floating |
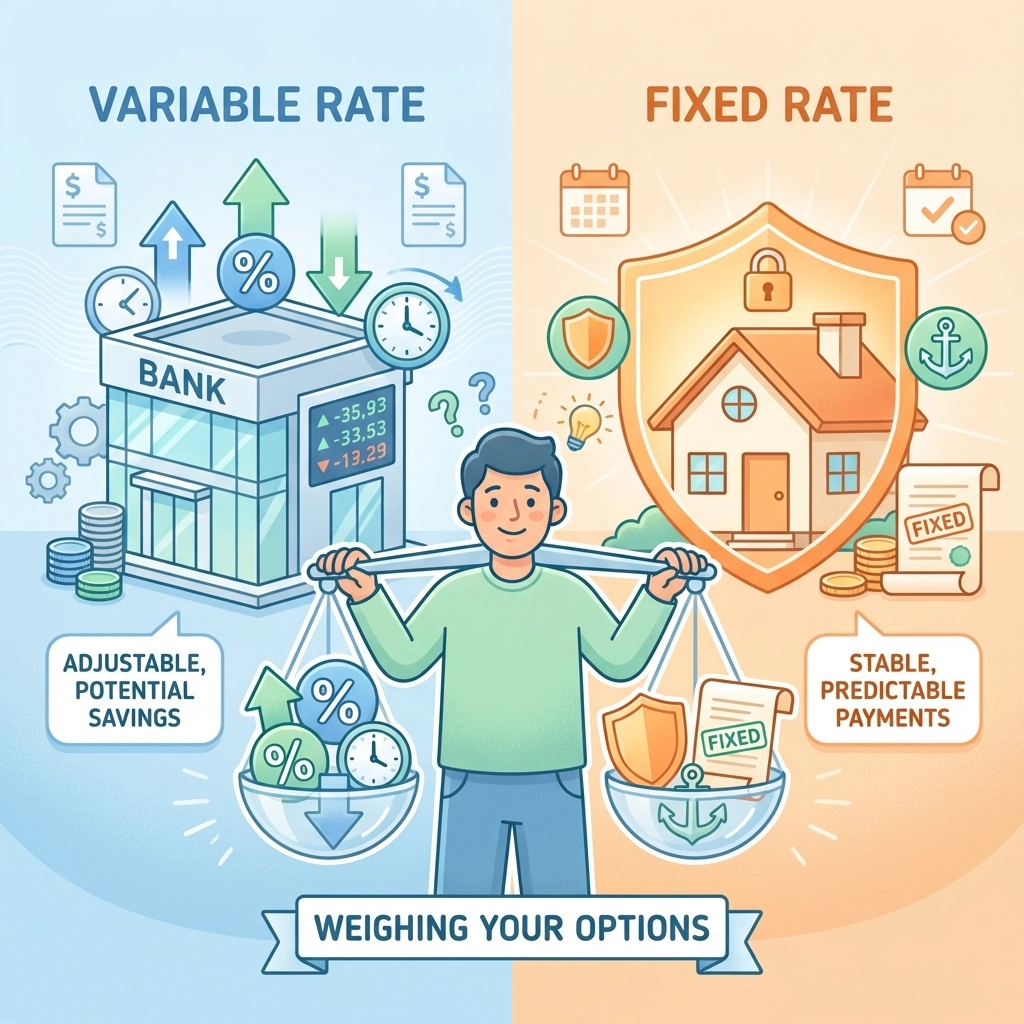
Fixed or floating: a fixed-rate package keeps your instalment the same for the fixed period (often 2–3 years), which makes payments predictable. Fixed rates can be higher than floating rates when you take the loan, and a lock-in often applies. A floating rate moves with a reference rate such as SORA, so instalments can go down or up. Check what rate applies after any fixed period ends.
When comparing banks, don’t just look at the headline rate. Check:
- Lock-in period penalties
- Repricing fees after fixed period ends
- Partial prepayment terms
- Clawback clauses on subsidies
Step 5: The Big Decision, Sell First or Buy First?
This is where most HDB upgraders get stuck. Both options have trade-offs, and the right choice depends on your cash position and risk tolerance.
Option A: Sell HDB First, Then Buy
Pros:
- Maximum 75% LTV (lower down payment)
- Full sale proceeds available for new purchase
- No dual mortgage stress
- Better TDSR position
Cons:
- Need temporary housing (rental costs $3,000–$5,000/month)
- Risk of property prices rising while you search
- Logistical hassle of moving twice
Option B: Buy Condo First, Sell HDB Later
Pros:
- Seamless transition, move once
- Can renovate new place before moving in
- No rental limbo
Cons:
- Only 45% LTV (massive down payment required)
- Must service two mortgages temporarily
- ABSD applies (refundable if you sell HDB within 6 months)
Factors to consider before you decide
- Debt limits (MAS): banks must keep your total monthly debt repayments within 55% of your gross monthly income (Total Debt Servicing Ratio, TDSR). For an HDB flat, or an executive condominium whose minimum occupation period hasn’t ended, property loan repayments must also stay within 30% (Mortgage Servicing Ratio, MSR). If you hold two property loans at once, both count towards TDSR. They count towards MSR only when the new purchase is an HDB flat or EC. MAS
- How banks test affordability (MAS): for residential property loans, banks work out your repayments using the higher of a 4% floor or the loan’s “thereafter” rate, not just today’s rate. MAS
- Loan-to-value and cash downpayment (MAS): with no outstanding housing loan, a bank can lend up to 75% of the property’s value, with at least 5% paid in cash. With one outstanding housing loan, the limit is 45%, with at least 25% in cash. Lower limits apply if the tenure is over 30 years (25 for HDB flats) or runs past age 65. MAS
- Loan tenure (MAS): bank loans are capped at 30 years for HDB flats and 35 years for non-HDB properties.
- Lock-in and penalties: check the lock-in period, the penalty for repaying or refinancing during it, and any clawback of legal or valuation subsidies.
- Cash and CPF needed: the minimum cash downpayment, stamp duties and legal fees, plus rent in between if you sell first. CPF use is subject to CPF rules.
- Buffer for rate changes: look at how your monthly instalment would change if rates rise, and how long your cash could cover two loans or rent.
The choice depends on your own finances. Consider speaking to your bank or a licensed financial adviser.
Every figure is from MAS’s housing-loan pages, checked 17 Oct 2026 (SGT). The CPF Valuation and Withdrawal Limits and ABSD remission are left out because they weren’t verified here.
Step 6: Using your CPF for the purchase
CPF Ordinary Account savings can be used for eligible property costs, subject to CPF rules.
What CPF can cover:
- Down payment (up to 20% of purchase price)
- Stamp duties
- Monthly mortgage payments
- Legal fees
What you need to know:
- If you own more than one property funded by CPF, your Basic Retirement Sum must remain untouched
- CPF usage is subject to Valuation Limit (VL) and Withdrawal Limit (WL)
- For properties over 30 years old, CPF usage is restricted
Using CPF or cash: using CPF Ordinary Account savings for eligible costs keeps more cash on hand for renovation, furniture and emergencies, but leaves less in your OA for later instalments and other uses. Paying in cash keeps your CPF savings intact but uses up cash reserves. When you sell the property, you must refund the CPF savings you used, plus accrued interest, to your CPF account from the sale proceeds. If you sell at market value and the price doesn’t cover the outstanding loan and the refund, you only refund the selling price minus the outstanding loan, with no cash top-up. CPF use is subject to CPF rules. (Source: CPF Board)
For more insights on property investment strategies, check out our guide on best Singapore districts for property investment.
Step 7: Your Complete Upgrade Financing Checklist
Before you sign anything, make sure you’ve ticked these boxes:
Documentation Prep:
- [ ] Latest 3 months payslips
- [ ] Latest income tax Notice of Assessment
- [ ] CPF contribution history (12 months)
- [ ] Outstanding loan statements
- [ ] HDB flat valuation report
Financial Readiness:
- [ ] Emergency fund (6 months expenses) separate from property funds
- [ ] Renovation budget set aside
- [ ] Stamp duty cash ready
- [ ] Buffer for interest rate increases (stress test at +2%)
Strategic Decisions:
- [ ] Sell-first or buy-first decision made
- [ ] Bridging loan options explored (if buying first)
- [ ] ABSD remission timeline understood
- [ ] Mortgage pre-approval obtained

Final Thoughts: Play the Long Game
Upgrading from HDB to condo or EC is one of the biggest financial moves you’ll make. Small differences in rates and fees add up over a long loan tenure.
Take your time with the numbers. Get multiple bank quotes. Stress-test your budget against rate hikes. And whatever you do, don’t let FOMO push you into a purchase you can’t comfortably afford.
Your dream condo isn’t going anywhere: but your financial health should always come first.
Looking for more property insights? Explore our 2026 new property launches analysis or browse best areas for property investment in Singapore to make your next move with confidence.
RELATED POSTS
View all

39 Best Private Driving Instructor Singapore: Free List
November 12, 2024 | by nearme.sg
Singapore New Property Launches 2026: In-Depth Analysis
January 6, 2026 | by nearme.sg
New Executive Condo Rules 2026: Expert Property Investment Strategy
May 9, 2026 | by nearme.sg